


Which Silver IRA provider deserves retirement savings when nearly every dealer promises education, secure storage, and rollover assistance? Compare the details that shape the account: dealer markups, custodian responsibilities, storage contracts, and the cost of selling.
The best Silver IRA is an arrangement that fits your retirement plan and makes its total costs clear. Check the custodian and the price before weighing a salesperson's reputation. If inflation is a concern, compare I Bonds and TIPS before deciding whether physical silver belongs in your portfolio.
Each provider below receives the same four-part review: fees, custodian structure, storage, and reputational checks. This is a comparison, not a ranked countdown or a certification of current operations. Verify company-specific fee schedules, contracts, and regulatory records before funding an account.
Gold IRA Association is an online information resource, not a metals dealer or custodian. Its materials are for informational purposes and are not financial, legal, or investment advice. Consult a qualified professional about decisions specific to your situation.
1. Augusta Precious Metals
Before funding a Silver IRA, understand who handles each part of the account. A dealer arranges the precious-metals purchase, a custodian administers the IRA, and a depository holds the silver. Read the account and storage documents to confirm each party's responsibilities, including whether storage is segregated.

The main risk is relying on a sales presentation instead of written terms. Ask for a complete fee breakdown covering setup, administration, storage, insurance, transactions, and product premiums. Then check the account documents to see which institution handles transfers, statements, distributions, and liquidation instructions. Confirm the storage facility, custody arrangement, insurance terms, and segregation in the agreement.
For an illustrative rollover, a pre-retiree moves part of a former employer's traditional retirement plan into a precious-metals IRA. The receiving custodian coordinates with the plan administrator so funds move directly rather than being paid to the investor.
The IRS rollover guidance generally allows 60 days to complete an eligible rollover after receiving a distribution. It also limits IRA-to-IRA indirect rollovers to one in any 12-month period. Direct transfers and plan-to-IRA direct rollovers use different paperwork, so confirm which process applies before funds move.
Use this Silver IRA basics guide to prepare questions about account rules and written terms. Gold IRA Association offers educational resources, but those materials do not replace advice specific to your situation. Precious-metals investing and IRAs involve risk, including the potential loss of principal.
2. Goldco
Before choosing any precious-metals IRA provider, examine how an eventual sale would work. Buyback terms matter because the price offered and the conditions attached affect the proceeds you may receive.
Compare the account and the exit together
Fees: Compare the purchase premium and liquidation spread, along with annual administration costs. Request a product-specific purchase quote and a contemporaneous sell-back estimate for the same silver. Treat a buyback program as a transaction policy, and price the exit before buying.
Custodian structure and storage: Identify the institution that maintains the IRA, who reports distributions, and which depository holds the assets. Check whether insurance and storage are itemized or included in a bundled fee. These details affect the account's ongoing costs and how its assets are held.
Reputational checks: Review complaint records, state regulator information, and the substance of unresolved disputes. A rating alone cannot show how a provider handles pricing disagreements or delayed transactions.
For a saver weighing traditional and Roth treatment, the decision should start with the proposed funding transaction. A tax professional can assess any conversion tax and the rules for future withdrawals. Do not assume every Roth withdrawal will automatically be tax-free.
The SEC investor alert on self-directed IRAs warns about higher fees and liquidity risks in alternative-asset accounts. Use that guidance to scrutinize costs and how readily you could sell. Get the buyback conditions in writing and review how the price will be determined before making a purchase.
The Silver IRA reviews resource can help organize your research. Favor a documented exit process over a general assurance that selling will be easy. Compare providers using the same four checks: fees, custodian structure, storage, and reputational records. Then choose based on the written terms and your own retirement needs.
3. Birch Gold Group
A privately minted silver round needs a clear eligibility trail before an IRA purchase. Record its manufacturer, weight, fineness, and product description, then get the custodian's approval before authorizing payment. This product-level check helps distinguish eligible bullion from items that may be treated as collectibles.
Confirm eligibility before choosing products
The IRS guidance on IRA investments explains the rules for prohibited collectibles and exceptions for qualifying coins and bullion, including one-ounce silver coins minted by the U.S. Treasury. For silver bullion, check the .999 fineness standard and ask the custodian to confirm that the exact product meets all applicable requirements.
Product descriptions should match across the quote, purchase paperwork, and account records. If a quote lists collectible-style coins, compare it only with another quote for the same kind of product. Silver content alone does not make two purchases equivalent.
Keep the review focused on the transaction itself. Ask for the full cost of the selected items and identify which expenses recur. Confirm who administers the IRA and which records the custodian needs to approve the purchase. Then check that the product description on the invoice can be matched to the depository's inventory record and the custodian statement.
A clear paper trail makes later account reviews easier. Before authorizing payment, make sure the documents state what the IRA will own, why the custodian accepts it, and what the purchase costs. Keep the product details and approval together with the account records so you can refer to them if questions arise.
Choose products only after the eligibility decision is documented. That keeps the account focused on the investor's intended silver allocation and reduces confusion between bullion and collectible-style items.
4. Noble Gold Investments
How will the silver IRA be held, documented, and charged? Those details matter more than a simple account setup conversation. Noble Gold facilitates Gold and Silver IRAs and sells physical bullion, so focus on whether the proposed arrangement fits the intended silver allocation without unnecessary products or complexity.
Start with the custody records
The IRS's IRA guidance explains the custody requirements for qualifying bullion. IRA silver must remain in the appropriate trustee or custodian arrangement rather than being personally stored by the account owner. Confirm who administers the IRA, which depository holds the assets, and what documents describe the insurance and the process for resolving inventory discrepancies.
Custody checkpoint: The purchase invoice, custodian statement, depository record, and insurance description should identify consistent holdings.
Then calculate the full cost for the amount of silver you plan to hold. Fixed account expenses can weigh more heavily on a smaller allocation, so compare initial and ongoing charges using the same proposed investment and storage arrangement. A larger balance in a sales illustration can obscure what the account will cost for your intended amount.
For example, a pre-retiree might transfer part of an existing traditional IRA into silver while keeping other retirement investments elsewhere. Before buying, compare the proposed account's total costs with alternatives based on identical silver products and storage terms. This keeps the comparison focused on the arrangement, rather than on a different allocation or product mix.
Review current complaints and regulatory records, including how the company responds to reported issues. A shortlist requires documented custody terms, not an easy onboarding call. Make sure the paperwork clearly connects the silver purchased to the IRA, its custodian, and its storage records.
5. American Hartford Gold
How should you judge a precious-metals IRA that holds both silver and gold? Focus on the actual products, account arrangements, and costs rather than a blended account total. Combining metals does not remove product-specific premiums or transaction charges, and a single total can conceal an expensive product.
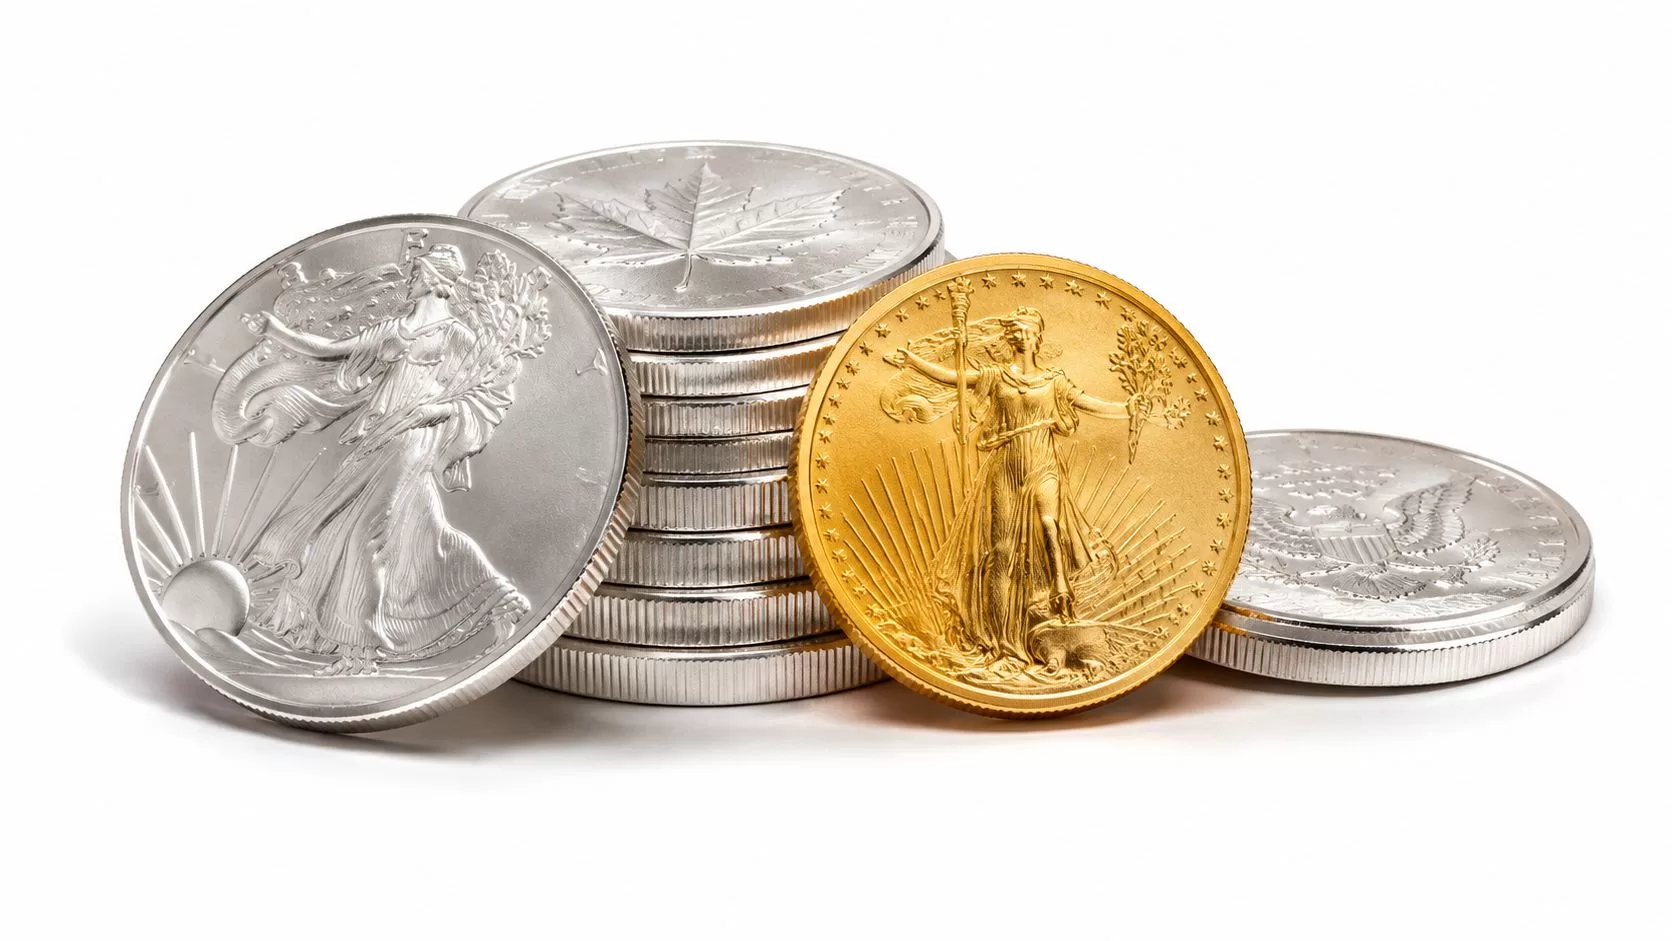

Before choosing a mixed-metal allocation, decide how much silver exposure fits your retirement plan and compare the proposed products' costs separately. Silver's industrial demand is part of the market context: the Silver Institute's supply-and-demand review reports industrial demand of 680.5 million ounces in 2024 and a total market deficit of 148.9 million ounces. These figures describe supply and demand, but they do not protect an investor from price declines. Precious metals can lose value, so an allocation should account for that risk.
Check the products and account details
Request separate purchase prices and expected resale prices for each metal. Compare the proposed items and charges, not just the combined total.
Confirm that the custodian accepts every proposed product and that the depository records each holding accurately. For silver bullion, check the exact product's fineness and manufacturer against the applicable IRA requirements rather than relying on a dealer's general description.
For a practical review of warning signs, read this precious-metals IRA scam guide. Use it to recognize pressure tactics and unclear pricing, then assess any specific transaction on its documented terms.
A mixed-metal account may simplify administration, but it does not guarantee lower costs or protect savings from market losses. Compare each product's price and the account's arrangements before approving a purchase.
6. Lear Capital
A silver IRA quote deserves close scrutiny at the product level. Compare the amount of silver you receive with the premium, potential resale proceeds, and ongoing account expenses before approving an order.
For example, compare an American Silver Eagle with an eligible silver bar. Assess each product using the same measures: silver weight, purchase premium, expected resale proceeds, and account costs.
Calculate the premium before approving the order
The premium over spot is the retail price minus the theoretical metal value, divided by that metal value. Calculate theoretical metal value by multiplying the silver weight by the contemporaneous spot price.
The CFTC's precious-metals advisory warns that some fraudulent dealers have charged spreads above 300% and recommends checking what the metal could fetch if sold back promptly. Use that warning to examine the quote, not to draw conclusions about any particular dealer.
- Fees: Compare the premium, commissions, account charges, shipping, and expected liquidation deductions.
- Custodian structure: Identify the independent administrator and who receives sale instructions.
- Storage: Verify the depository, insurance scope, inventory method, and distribution procedures.
- Reputational checks: Review current and historical regulatory records, settlements, and complaint resolutions. Look for clear documentation.
Pricing rule: A low annual account fee doesn't make an expensive silver product economical.
A break-even review should show how much sale proceeds must rise to recover the initial purchase cost and accumulated account expenses. Keep that calculation separate from any forecast of silver prices.
Choose based on evidence: a clear quote, confirmation that the products are eligible, documented custody arrangements, and satisfactory business records. Name recognition alone cannot establish whether the costs and terms suit your retirement account.
7. JM Bullion
How do you tell whether an online silver price reflects the cost of an IRA purchase? JM Bullion sells physical precious metals and supports IRA purchases through third-party account relationships. Evaluate the product and the account arrangement separately.
A displayed product price is only a starting point. The final IRA cost can also depend on custodian, storage, payment, and transaction terms.
Turn an online price into an account quote
Before ordering, save the descriptions of eligible silver coins and request an IRA-specific total. Confirm that the receiving custodian accepts those exact products and that delivery follows the designated custody process.
The quote should answer practical questions: What will you pay to buy, hold, and eventually sell the metals? Who administers the account, and where will the metals be stored? Check the written terms rather than relying on a retail product page.
- Fees: Reconcile the displayed product price with the executable purchase quote and ongoing account costs.
- Custodian structure: Identify the institution that opens and administers the IRA, and clarify which services the dealer handles.
- Storage: Confirm the receiving depository, delivery instructions, inventory records, and insurance coverage.
- Reputational checks: Distinguish reviews of direct purchases from complaints about retirement-account transactions or third-party administration.
Browsing products independently can help you assess the selection on your own terms. A coin's design or a visible discount does not establish IRA eligibility or a favorable resale spread. Verify eligibility first, then consider market demand. The Silver Institute's review of industrial and investment demand reports that global coin and net-bar demand fell 22% to 190.9 million ounces in 2024.
Before placing an order, match the exact product and quantity on the retail page to the executable IRA quote. Include ongoing account costs, and resolve any difference before authorizing the purchase.
8. Regal Assets
Is a precious-metals provider operating now, accepting accounts, and able to document its custody arrangements? Confirm those points before considering any transfer. Older comparisons do not establish current status.
Verify the business before comparing storage
Start with specific checks: confirm the legal entity and current operating status, review relevant state regulator records and enforcement history, and examine outstanding complaints. If you cannot verify the business and its account process, do not transfer retirement funds.
Request current account documents from the dealer and the independent custodian. Confirm which institution opens and administers the IRA, and what responsibilities belong to each party. Archived brochures, reviews, and promotional videos cannot establish the terms of a current account.
Storage terms describe different arrangements. Read the contract to see how each one handles ownership and records:
- Allocated holdings: Account records identify the metal held for the account. Check how the agreement documents ownership.
- Segregated holdings: The agreement specifies that metals are stored separately and explains the terms.
- Non-segregated holdings: The contract should describe commingling, recordkeeping, and what property is returned upon distribution.
When comparing storage arrangements, read the contract rather than relying on reassuring labels. Check how inventory is recorded, what insurance exclusions apply, what withdrawal rights the agreement provides, and which charges apply.
The video below is background material only. It does not verify current services or regulatory standing.

Keep the order clear: establish current operating status and custody arrangements first. Compare storage terms only once those details are documented and understandable.
Best Silver IRA Providers at a Glance
A provider name alone does not tell you whether an account fits your needs. Use the same four-part screen for each option: fees, custodian structure, storage, and reputational checks. This roundup is not a ranked countdown. It is a way to compare the terms that shape account costs, custody, and access to your metals.
| Evaluation area | What to compare |
|---|---|
| Fees | Check the full fee schedule and distinguish account charges from product pricing. |
| Custodian structure | Identify the custodian and clarify its responsibilities for account administration and transactions. |
| Storage | Review the depository arrangement and the contract terms for how holdings are stored and documented. |
| Reputation | Examine current business information and available customer feedback; look for clear answers to your questions. |
Treat each row as a question to resolve, not a score. Ask providers for current documents, then compare equivalent terms. A low product price does not show the account's total cost, and a storage label alone does not explain how holdings are handled. Confirm which party administers the IRA, who holds the metals, and which fees apply at each stage.
Use the comparison to identify what still needs clarification. If a provider cannot explain its fees, custody arrangements, storage terms, or business information clearly, pause before deciding. Your circumstances and priorities determine which terms deserve the closest attention, so compare the documents rather than relying on broad descriptions.
Your Silver IRA Buyer Checklist and Next Step
The best Silver IRA combines transparent pricing, eligible products, independent custody, documented storage, and a workable exit. Sales assistance matters, but it doesn't compensate for missing contracts, unexplained markups, or unresolved questions about a business's current standing.
Use the same checklist for every provider:
- Written all-in costs: Collect the product premium, commissions, setup charges, annual administration, storage, insurance, shipping, and liquidation expenses.
- Identified custodian: Verify the institution's legal name, account agreement, responsibilities, and distribution procedures.
- Documented depository: Confirm its eligibility to hold IRA assets, storage arrangement, insurance terms, and inventory reporting.
- Product eligibility: Record the mint or refiner, weight, fineness, and custodian acceptance before purchase.
- Independent reputation review: Examine current operating status, regulatory records, complaint patterns, and responses.
- Practical exit plan: Obtain a sell-back estimate and identify who authorizes sales, settles proceeds, and processes distributions.
Plan for withdrawals before buying
Retirement distributions deserve attention before an account is funded. The IRS required minimum distribution guidance states that traditional IRA owners generally must begin RMDs at age 73, with the first generally due by April 1 of the following year; the applicable starting age should be checked against current rules and the owner's circumstances.
A physical-metal account may need a sale or an eligible in-kind distribution to satisfy withdrawal obligations. The investor and custodian should establish valuation, processing, and tax-reporting procedures before a deadline creates pressure to act.
Keep retirement spending needs separate from a long-term silver thesis. A compelling reason to own silver doesn't eliminate the possibility of selling at an unfavorable price.
Each provider considered here must earn approval through verification. None receives a blanket endorsement, and any candidate that fails operating-status, custody, pricing, or reputation checks should be removed from consideration.
Silver investing involves risk, including the potential loss of principal. A licensed financial advisor, CPA, or tax professional should review allocation, rollover, conversion, and distribution decisions in light of the investor's circumstances.
For educational help, Gold IRA Association accepts messages through its contact form and aims to respond within 24 hours. That support helps readers locate information about account rules and provider comparisons; it doesn't replace personalized professional advice.
Gold IRA Association publishes plain-English guides to Silver IRA rules, rollovers, eligible metals, fees, and provider comparisons. Visit Gold IRA Association to send a question through the contact form, or call 888-910-8386 for help finding educational resources before committing retirement funds.


