

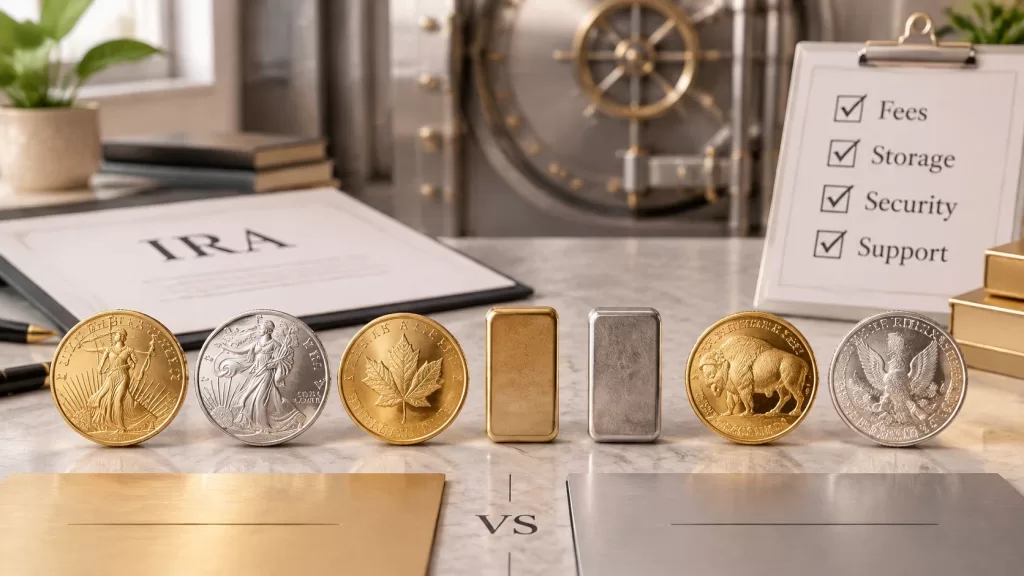
What if the metal inside the account matters less than the paperwork, custody, and pricing wrapped around it? Many near-retirees miss that gap when they search for the best self directed precious metals IRA, because the same IRS-eligible coin can carry very different premiums, storage terms, and liquidation costs depending on which provider sets up the account.
Each of the seven providers below is measured on the same operational checkpoints: custodian structure, storage arrangement, fee disclosure, metals menu, and rollover handling. That framing turns a brand comparison into a checklist the reader can run before requesting quotes, which matters because two companies can sell an identical product while charging for it in different places. A provider that looks cheaper on annual fees can still cost more at purchase or at sale.
Funding capacity adds one more distinction worth making before comparing providers. The IRS page on IRA contribution limits sets the combined annual contribution limit for an individual's traditional and Roth IRAs at $7,500 for 2026, rising to $8,600 for people age 50 or older. Rollover contributions sit outside that limit. That is why rollover handling earns its own checkpoint rather than being folded into general account fees: the way a provider moves an existing 401(k) or IRA determines speed, paperwork, and tax exposure, and none of that is governed by the annual cap.
1. Augusta Precious Metals
The first provider review should begin with role separation. A dealer quotes the coins or bars, a custodian administers the IRA, and a depository holds the metal. Educational support is useful when those responsibilities and costs are documented before the account is funded.
A provider's menu can include IRS-eligible gold, silver, platinum, and palladium, but eligibility cannot be inferred from a product name. A guide to precious metals IRA rules and setup states that gold bullion generally must meet fineness of at least 99.5% (0.995), silver generally 99.9% (0.999), and platinum and palladium generally 99.95% (0.9995), with the American Gold Eagle as a statutory exception at 91.67% gold.
A traditional 401(k) from a former employer may be moved through a direct rollover and allocated between American Eagle coins and bullion bars. The stronger quote separates each product's premium from setup, account administration, storage, and transaction charges. That makes two offers comparable on the same metal, custody arrangement, and exit terms.
What to confirm in writing
The video below offers additional context before the written checks begin.
- Custodian identity: Get the name of the firm administering the IRA and ask which charges it bills.
- Depository name: Confirm where metals are held and that they're held for the investor's IRA.
- Buyback method: Ask how buyback pricing is calculated and what conditions apply.
2. Goldco
The checks that decide whether a self-directed metals IRA is workable are who administers the account, where the metals are stored, what each product costs over spot, and how a later sale is priced. For this entry, treat those points as documents to request: custodian agreement, depository confirmation, product list with IRA eligibility marked, and a rollover timeline.
The custodian's role is administrative. The SEC guidance on self-directed IRAs warns that custodians generally do not assess the quality, legitimacy, liquidity, or expected performance of the underlying investment, and it identifies account-opening, annual administration, transaction, and asset-specific charges in the broader fee stack.
The image below reflects the paperwork stage where those separate roles should be documented.
Cost and custody checks
- Line-item premiums: Ask for premiums and fees for each product as separate totals.
- Storage record: Request the depository name and confirmation that metals are held for the IRA.
- Asset holder: Confirm the account assets sit with the custodian.
- Rollover handling: Ask who prepares transfer paperwork and how the funding steps are sequenced.
Readers comparing rollover handling can also review the guide to the best IRA rollover companies alongside any quote.
3. Birch Gold Group
Educational material is the first product a precious metals provider sells. Rollover guides explain IRS rules and metal selection well enough to earn trust, and in doing so they define which questions feel settled before a quote ever appears. The way to use them is as a map of what a provider wants asked, then spend attention on the items the map leaves out.
Strong demand figures often enter the conversation at this stage, and they deserve a narrow reading. The World Gold Council release on 2025 gold demand reported 2025 global gold investment demand of 2,175 metric tons and total demand of 5,002 tons. Those figures describe market depth. They say nothing about whether a specific provider's markup, storage fee, or buyback spread will treat an IRA balance well.
The desk image below fits the review step, where claims from guides get tested against documents.
Questions the guides leave open
- Custodian structure: Ask which custodian administers the account and get that custodian's fee schedule separately, rather than inside the dealer's quote.
- Metals menu: Ask which specific coins and bars are offered for IRA placement and check each product against IRS eligibility rules before choosing.
- Rollover handling: Ask whether the funds move trustee-to-trustee and who tracks each form until the transfer settles.
A broader comparison is available through the Gold IRA reviews hub for readers building a shortlist.
Practical rule: Educational material is useful only when the final quote, custodian agreement, and depository terms say the same thing in writing.
4. Noble Gold Investments
Every provider on this list is measured against the same five checkpoints: custodian structure, storage arrangement, fee disclosure, metals menu, and rollover handling. For this entry, the checkpoint that decides most outcomes is fee disclosure, because the setup fee is usually the smallest number in a precious metals quote. The larger costs sit in the spread between the purchase price and the eventual sale price, plus storage and administration charges that recur for every year the account stays open.
The stakes are documented. CFTC guidance on precious metals fraud and costs warns that some victims have lost one-third to one-half of their savings to markups, fees, and commissions. A compliant account can still produce a milder version of the same result when spreads run wide and annual charges stack up, which is why the round trip deserves more attention than any single line item.
The coins below illustrate why statement value and sale proceeds shouldn't be treated as identical.
All-in cost questions
- Two-way quote: Ask for today's purchase price and the price the dealer would pay to buy the same item back, in writing.
- Storage type: Check whether metals are segregated or commingled and how that's documented.
- Melt value gap: Ask why custodian melt value may differ from actual liquidation proceeds after spreads and selling charges.
Practical rule: A quote that prices the purchase but never the resale is only half a quote. Get the buy-back spread in writing before any funds move.
5. American Hartford Gold
A low minimum is useful only when the fixed costs stay small relative to the balance. The same annual charge that looks minor on a large rollover can become a meaningful drag on a test allocation, so fee disclosure has to be read as a percentage, not as a headline dollar figure.
An investor moving a modest 401(k) into a Gold IRA should treat the rollover path as part of the cost. IRS Publication 590-A on contributions and rollovers states that a rollover generally must be completed within 60 days after the account owner receives the distribution, and Internal Revenue Code Section 408(d)(3)(B) generally limits a taxpayer to one IRA-to-IRA rollover in any 12-month period. A direct trustee-to-trustee transfer avoids the participant receiving the funds.
Smaller balance math
- Fee drag: Divide total annual fees by the actual starting balance, then compare that percentage across quotes.
- Minimums in writing: Verify minimum investment requirements before opening paperwork.
- Independent pricing: Compare each product premium with independent price sources and a recognized spot benchmark.
A small account doesn't need the broadest metals menu. It needs the lowest clear round-trip friction that still provides compliant custody and storage.
The decision is therefore less about entry convenience and more about whether the first year leaves enough metal in the account to justify the spread, storage, and administration charges.
6. Advantage Gold
Rollover support is the main lens for Advantage Gold. Administrative help and metal pricing are separate tests, and a provider can handle the transfer cleanly while still quoting wide premiums. Score the paperwork quality and the quote quality independently.
A near-retiree moves an old 401(k) into a Gold IRA that will hold a mix of bullion bars and coins. Bars may look simpler than coins, but eligibility still depends on metal, fineness, and refiner or mint documentation. The test is whether each product qualifies for IRA ownership and enters approved custody without the account owner taking personal possession.
Custodian and product verification
- Qualified custodian: Ask for the custodian's name and confirm it's a qualified IRA custodian.
- Storage arrangement: Ask which depository holds the metals and whether storage is segregated or commingled.
- Product eligibility: Verify purity and eligibility against IRS guidance before purchasing.
A strong quote from Advantage Gold should identify the exact ounces, products, premium per ounce, storage method, and liquidation path. If any one of those items is described only verbally, the comparison isn't finished. A second quote using the identical product list gives the cleanest check.
7. Patriot Gold Group
A self-directed IRA shifts verification duties onto the account holder in ways a conventional IRA does not. The Investor.gov alert on self-directed IRAs identifies these accounts as carrying higher risks of fraud, high fees, and volatile performance, while IRS guidance says IRA assets cannot benefit disqualified persons. Those risks define the checkpoints any provider quote should answer: who the custodian is, where the metal sits, and what each recurring fee covers.
A partial rollover shows why the documentation burden matters. Moving part of a traditional IRA into a Gold IRA while leaving the rest in stocks and bonds takes the same transfer request, the same custodian acceptance, and the same per-product eligibility checks as moving the full balance. The paperwork does not shrink with the amount moved. Fixed costs grow heavier instead, since flat annual administration and storage fees consume a larger share of a smaller funded balance. That makes the fee schedule worth reading before the transfer form, not after.
Annual control checks
- Disqualified-person check: Confirm no IRA metal is stored at home or used for personal benefit, since IRS rules bar IRA assets from benefiting disqualified persons.
- Approved depository: Confirm metals are held at an IRS-approved depository for the IRA.
- Statement reconciliation: Check that statements reflect all bullion purchased and don't rely on an inflated price.
These checks repeat each year because the underlying risks do not expire after the first purchase. Readers who want warning signs before funding can consult the Gold IRA scam guide as part of that annual control mindset.
How the Seven Providers Compare on Metals, Custody, and Rollovers
Which provider wins a side-by-side comparison depends on what you put in the columns. A scorecard built around brand names collapses into a list of labels. A scorecard built around operating checkpoints produces answers you can verify. Run the same five questions against every provider and the differences surface in writing rather than in reputation.
| Checkpoint | Ask each provider | What a clear answer includes | Your notes |
|---|---|---|---|
| Custodian structure | Who serves as IRA custodian, and is that custodian independent of the dealer? | A named custodian, the account-opening documents it requires, and a statement of which party reports account activity | |
| Storage arrangement | Which depository holds the metal, and is the allocation segregated or commingled? | Depository name, whether the coins and bars sit in the account's name, and how insurance applies to stored metal | |
| Fee disclosure | What is the total first-year cost and the ongoing annual cost at this account size? | Setup, annual administration, storage, insurance and shipping listed as separate lines, plus how the dealer's spread on metal is set | |
| Metals menu | Which products are IRS-eligible, and at what minimum fineness? | A product list with fineness thresholds for gold and silver, and a direct answer on whether platinum or palladium is offered at all | |
| Rollover handling | Is the transfer direct trustee-to-trustee, and who prepares the paperwork? | Confirmation that funds never pass through the client, the forms required, and the expected timeline from request to funded account |
Two patterns are worth watching while the right-hand column fills in. A provider that will not name its custodian or depository before an account is opened gives you nothing to check later. A quote that bundles storage and insurance into a single number hides the line item most likely to move as the balance grows.
Matching inputs keeps the comparison honest. Ask every provider for the same metal, the same balance band and the same storage method. Where two answers are identical, price decides. Where they diverge, the divergence usually is the decision.
Keep the completed table. Filed next to the first account statement, it shows when a fee line changes or a depository name shifts, which is the point at which the original answers stop describing the account you own.
Choosing a Provider with Confidence
What happens when you need to take money out of a precious metals IRA? Plan for that before opening the account. A provider's process for selling or distributing metals can affect how practical the account is in retirement.
Plan for distributions before buying
IRS Publication 590-B on distributions states that traditional IRA owners generally must begin required minimum distributions at age 73 for tax years beginning in 2023 and later. The amount is generally calculated by dividing the IRA balance at the close of business on December 31 of the preceding year by the applicable factor. A required minimum distribution cannot be rolled over, so an account holder may need to sell or distribute enough metal to meet the annual requirement.
Ask how partial sales work, how long liquidation takes, what spread applies, and whether an in-kind distribution is available. These details help clarify the account's options at the point of distribution.
Investing in precious metals and IRAs involves risk, including the potential loss of principal. Gold IRA Association's website materials are for informational purposes only, not financial, legal, or investment advice. Readers can consult a professional advisor for advice specific to their situation.
Gold IRA Association offers educational resources, including guides and articles on Gold IRAs, rollovers, retirement planning, precious metals, and provider comparisons. Its reviews assess providers' credibility, customer service, fees, and investment options. Readers can also send a direct message to ask for help finding educational information about account rules and provider comparisons.