

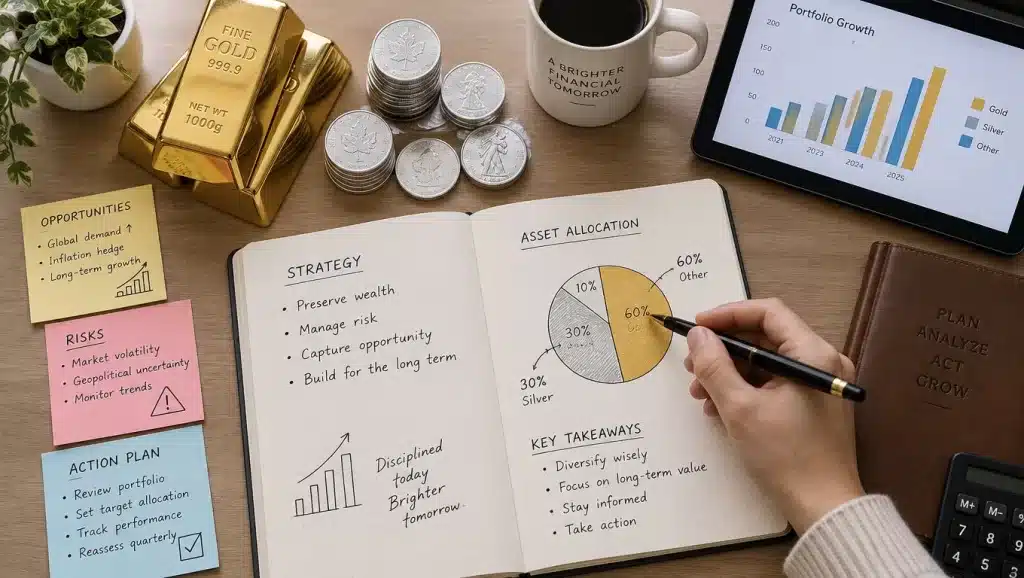
A near-retiree may have stocks, bonds, cash, and an employer plan, yet still not know how much gold or silver belongs in the mix. A general rule rarely answers the practical question, because the right allocation depends on liquidity needs, tax position, time horizon, and tolerance for price swings. The diversification strategy examples below use worked allocation models, risk profiles, trade-offs, and implementation steps. Each is a framework to test with a licensed financial advisor, CPA, or tax professional. This is not financial advice.
1. Asset Class Diversification Within Retirement Accounts
Asset class diversification starts with the broadest decision, how retirement savings are divided among stocks, bonds, cash, real estate, and precious metals. The SEC describes diversification as spreading money across asset categories and across different investments within each category, while also cautioning that diversification reduces risk but doesn't eliminate investment losses. The SEC's asset-allocation guidance supports treating precious metals as one possible category, not as a complete portfolio.
A moderate model might move a portion of a 70% stock and 30% bond portfolio into metals, producing 60% stocks, 25% bonds, and 15% precious metals. That allocation still leaves most assets in growth and income holdings, while giving gold or silver a defined role. A couple might instead use a Roth Gold IRA to hold physical silver for long-term diversification, while keeping other retirement assets in conventional investments.
Risk profile and trade-offs
This model may suit an investor who wants a tangible-asset allocation without allowing metals to dominate retirement savings. Its main advantage is role clarity. Stocks may provide growth, bonds may support income and stability, and precious metals may offer a different response to inflation, currency concerns, or equity stress.
The trade-off is that physical metals can involve setup, custodial, storage, insurance, and transaction costs. Metals also don't produce dividends or interest, so an investor relying on portfolio withdrawals needs liquid cash-flow assets elsewhere.
Practical rule: Judge the allocation by total household exposure, not by the balance of one IRA alone.
Implementation step
List every account and holding, then calculate exposure by asset class and sector. Confirm that proposed products meet current IRS rules. The IRS generally requires IRA-eligible gold to meet .995 fineness and silver to meet .999 fineness, but product eligibility and approved refiners should be verified with the custodian before purchase. Compare all account and storage costs before deciding whether the proposed allocation fits the retirement plan.
2. Rollover Diversification From 401(k) and Traditional IRA Funds
A rollover can change asset allocation without requiring an investor to liquidate an entire retirement strategy. For example, an employee with $400,000 in a 401(k) might initiate a direct rollover, place $75,000 into IRA-eligible gold and silver, and keep $325,000 in a self-directed brokerage IRA for stocks and bonds. The model separates the metals decision from the rest of the portfolio instead of treating a rollover as an all-or-nothing move.
A direct trustee-to-trustee transfer is generally simpler than sending funds to the participant. The IRS states that a participant-paid 401(k) rollover generally must be completed within 60 days, and that a taxable eligible distribution paid to the participant generally faces 20% federal withholding. The IRS rollover guide explains that the full original amount usually must be deposited to complete the rollover, which may require replacing the withheld funds.
Risk profile and trade-offs
This strategy may reduce concentration in an employer plan, but it creates administrative risk. A delayed transfer, incomplete deposit, or misunderstood tax treatment can undermine an otherwise sensible allocation. Investors with multiple IRAs, ongoing contributions, or a pension-related distribution should obtain tax advice before moving funds.
A recently divorced investor may also use a Qualified Domestic Relations Order, or QDRO, to transfer an assigned portion of an ex-spouse's 401(k) into the investor's own retirement account. The receiving custodian, plan administrator, and tax professional should confirm the procedure before funds move.
Implementation steps
- Choose the receiving custodian first: Obtain account instructions before requesting the distribution.
- Request a direct transfer: Ask the existing plan administrator to send funds directly to the new custodian.
- Keep documentation: Save transfer dates, amounts, account statements, and confirmation from both institutions.
- Check the allocation afterward: Verify that the rollover produced the intended mix of metals, stocks, bonds, and cash.
A five-step visual can help readers understand how metals fit into a broader retirement allocation:
The process can also be explained through this educational video:
3. Geographic and Geopolitical Diversification
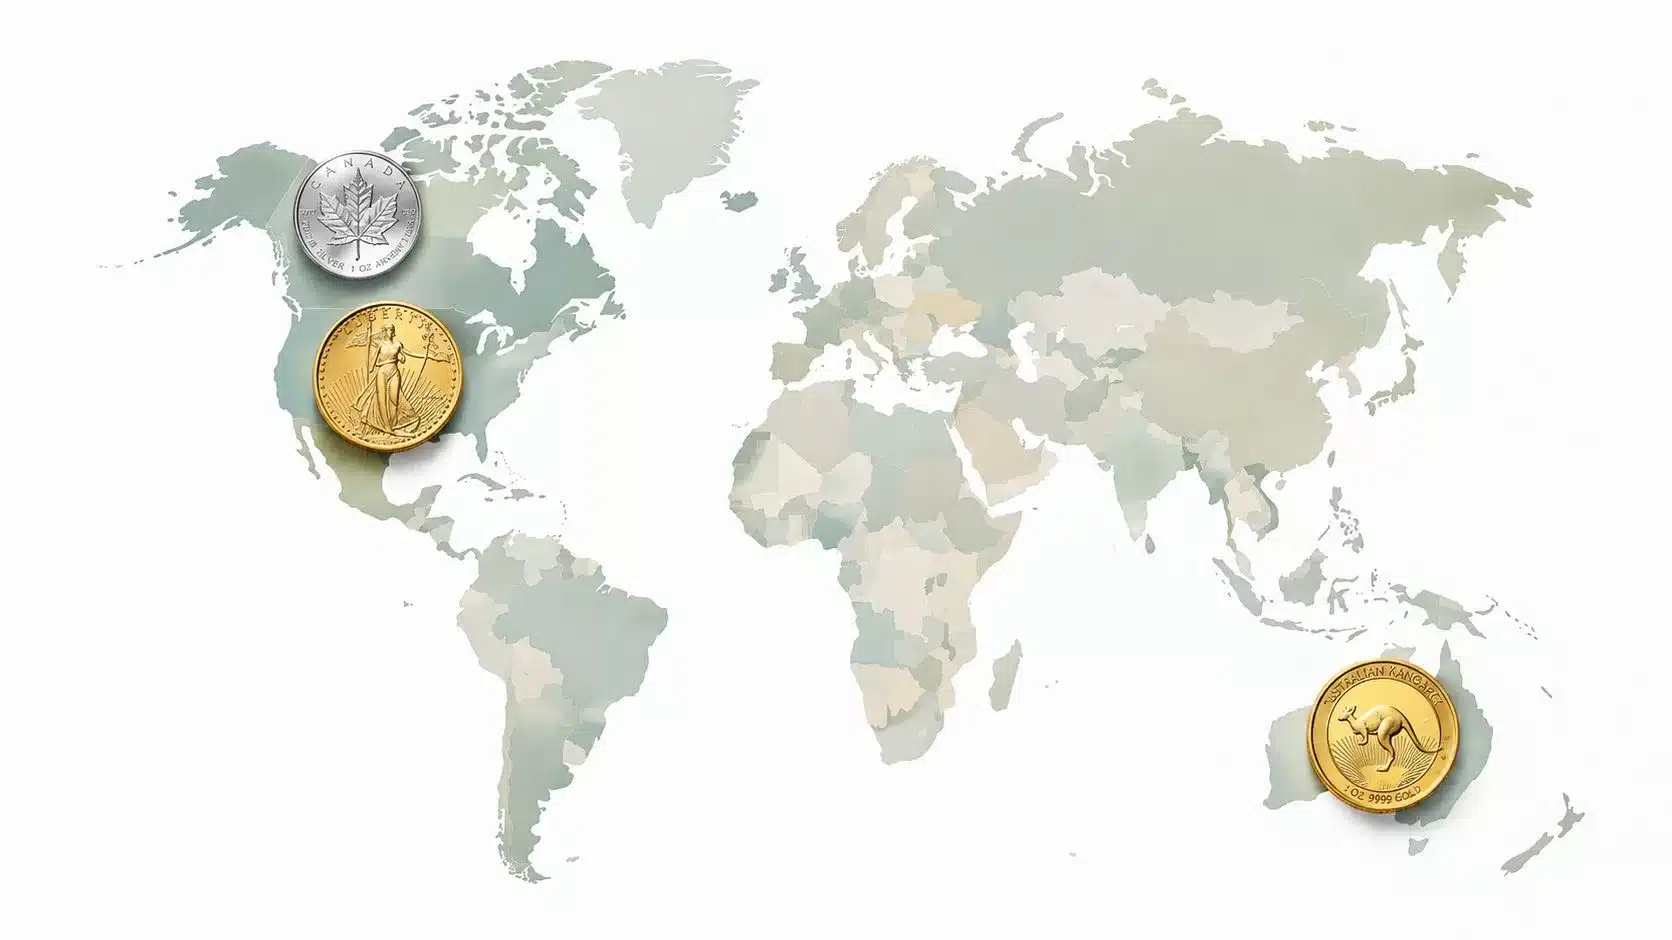
An investor who wants every metals dollar spread across jurisdictions is really asking about premiums, eligibility, and resale markets, not safety alone. One illustrative Gold IRA model could hold 40% domestic bullion coins, 30% foreign bullion coins, 20% refiner bars, and 10% specialty coins. The percentages describe a possible allocation, not a universal recommendation.
A retiree concerned about long-term dollar stability might add foreign-issued bullion alongside bars from established refiners, provided the custodian confirms each product's eligibility. The intended benefit is narrower than protection from geopolitical risk. Different origins and formats may reduce dependence on one producer, design, premium structure, or resale channel, while the underlying metals can still move together.
| Risk profile | Trade-offs |
|---|---|
| Moderate concentration reduction within a precious-metals allocation. | Geographic variety may broaden resale options, but it does not remove price volatility, currency-related effects, or dependence on precious-metals demand. |
| Greater product and jurisdictional spread than a single-origin holding. | IRA custody and storage rules still apply. Foreign origin does not mean the investor stores assets overseas. |
| Potentially useful for an investor focused on product flexibility. | Different premiums, availability, and valuation methods can make records and comparisons harder to maintain. |
Implementation should follow the allocation, rather than precede it:
- Confirm eligibility: Ask the custodian to approve each coin or bar under current IRS rules before ordering.
- Set category targets: Assign purchases to domestic bullion coins, foreign bullion coins, refiner bars, and specialty coins according to the model.
- Compare total costs: Review spot price, dealer premium, storage charges, and likely resale value for each category.
- Maintain product records: Track type, weight, producer category, purchase price, and account location.
- Review concentration: Recheck whether one product, origin, or resale market has become disproportionately large.
Geographic diversity remains secondary to liquidity, compliance, and total cost. International sourcing does not create meaningful diversification if every holding responds to the same precious-metals price movement.
4. Combining Gold, Silver, and Platinum
A single self-directed IRA can potentially hold more than one eligible precious metal, subject to current rules and custodian approval. Gold, silver, and platinum have different industrial uses and supply characteristics, so a mix may avoid placing every metals dollar into one price cycle. That distinction matters because adding several gold coins from different mints is product diversification, while adding silver or platinum changes the underlying exposure.
Consider a $300,000 Gold IRA allocated as 50% gold, or $150,000, 35% silver, or $105,000, and 15% platinum, or $45,000. The model has gold as the anchor, silver as a larger secondary exposure, and platinum as a smaller position with potentially different market drivers.
Risk profile and trade-offs
Silver may be more volatile than gold, while platinum can also experience substantial price variation. Those qualitative differences mean a multi-metal allocation may diversify exposure, but it can also increase the account's overall fluctuations. Premiums, liquidity, and product availability can vary by metal and market conditions.
A separate comparison of platinum and palladium in retirement accounts can help investors understand why adding a less familiar metal requires more than selecting a label on an order form.
A broader metals menu doesn't automatically create a safer portfolio. The investor still needs to identify which risk each holding is meant to offset.
Implementation steps
Set a written target before buying. A model such as 50% gold, 40% silver, and 10% platinum, or 60% gold, 30% silver, and 10% platinum, can clarify the intended role of each metal, but neither model fits every investor.
Next, confirm eligibility for every product. Platinum bars generally need to meet .9995 fineness, and approved coins must be checked individually. Finally, establish a review date and decide how much drift is acceptable before rebalancing. Without that rule, a volatile silver or platinum position can become larger than intended.
5. Strategic Rebalancing and Dollar-Cost Averaging
A retiree with a $500,000 portfolio may decide that precious metals should represent 15%, or $75,000. Rather than investing that amount at once, the investor could contribute $625 per month toward the allocation over 120 months, provided the portfolio value and contribution remain unchanged. This example describes a funding schedule, not an estimate of future prices or account value.
The schedule has a defined risk profile: it may reduce the timing risk of committing the full amount immediately before a decline, while leaving the portfolio underweight for an extended period. Dollar-cost averaging does not guarantee gains or prevent losses. Its practical value depends on whether the investor can continue contributions through price fluctuations.
Rebalancing addresses a separate problem. After market movements change the portfolio's proportions, the investor restores the intended mix instead of allowing one category to dominate by default.
How the process works
Set the target metals allocation and record why it fits the broader retirement plan. Choose either a calendar review or a threshold review. The SEC describes scheduled reviews, such as every six or twelve months, and reviews triggered when an allocation moves beyond a predetermined range. The SEC's rebalancing explanation explains both methods.
At each review, compare the current allocation with the written target. If metals have grown beyond the intended weight, the investor could sell enough to restore balance and direct the proceeds toward underweighted stocks, bonds, or cash. A retiree who wants to limit sales may instead direct new contributions toward those underweighted categories, where account rules permit.
The implementation record should include the allocation rationale, review date, drift threshold, account records, transaction confirmations, and updated allocation worksheet. Those details make the strategy repeatable rather than dependent on market headlines or short-term judgment.
Rebalancing controls exposure; it does not predict the next winning asset. Dollar-cost averaging controls the pace of contributions; it does not remove investment risk. Together, the two processes can keep the portfolio closer to its chosen design, subject to costs, liquidity, and the investor's ability to maintain the schedule.
6. Inflation-Hedging Diversification With Real Assets
Inflation can reduce the purchasing power of retirement income, particularly when withdrawals depend heavily on cash or fixed payments. Precious metals may serve as one real-asset hedge, but the evidence does not support treating them as a complete inflation solution. A portfolio still needs liquid reserves and assets capable of producing cash flow.
A more aggressive illustration involves a 62-year-old retiree with a $400,000 traditional IRA moving 20%, or $80,000, into a Gold IRA while keeping the remainder in diversified stocks and bonds. That model gives inflation concerns a visible place in the plan, but it also creates a larger exposure to an asset that doesn't pay interest or dividends.
Risk profile and trade-offs
A retiree using this approach may be prioritizing purchasing-power concerns over near-term income generation. Gold and silver can behave differently from stocks and bonds, yet their prices can also fall, and they may not track inflation consistently over every period.
A more balanced inflation strategy could combine a smaller metals allocation with Treasury Inflation-Protected Securities, real estate, commodities, or dividend-oriented equities. The correct comparison is not just nominal performance. It includes liquidity, income, costs, volatility, and the timing of withdrawals.
For a plain-language discussion of gold as an inflation hedge, investors should still compare the proposed metals position with other assets serving the same purpose.
Implementation steps
Define the inflation risk first. Is the concern rising living costs, currency weakness, bond sensitivity, or insufficient income? Then assign each holding a job and test the portfolio under inflation, recession, deflation, and strong-growth conditions.
Avoid changing the allocation solely because an inflation indicator moves. A written review schedule can prevent a temporary headline from turning a hedge into a concentrated bet.
7. Roth and Traditional IRA Account Structure
A household nearing retirement could place a 401(k) rollover into a Traditional Gold IRA while the employed spouse builds a precious-metals position in a Roth IRA. The accounts might hold similar assets, yet their tax treatment and withdrawal roles would differ. This creates diversification by account type, not merely by investment category.
The Traditional structure generally offers tax-deferred treatment, while Roth contributions are made after tax and qualified withdrawals may be tax-free, subject to eligibility and applicable rules. The choice therefore depends on expected tax exposure, withdrawal timing, and estate objectives as much as on interest in metals.
Allocation model and trade-offs
The Traditional account may suit an investor who values a current tax deduction and expects a lower tax rate later. The Roth account may suit someone who expects higher future tax rates, has a longer horizon, or wants flexibility through potentially tax-free qualified withdrawals. Age and income alone do not establish which outcome is more likely.
A practical model assigns each account a distinct job. The Traditional IRA could support planned retirement spending, while the Roth IRA could remain invested for later withdrawals or heirs. That arrangement may improve tax flexibility, but it can also complicate conversions, aggregate IRA calculations, income eligibility, and required distributions.
Set-up sequence
- Map the tax position. Compare present tax circumstances with plausible retirement conditions.
- Assign account roles. Decide which account may fund earlier withdrawals and which may be preserved.
- Verify the transaction. Confirm contribution, rollover, conversion, and withdrawal rules before acting.
- Compare after-tax outcomes. Model the same metals allocation in both structures, including withdrawal timing and applicable taxes.
- Review with a tax professional. A CPA or other qualified adviser can test assumptions that a general allocation review may miss.
The precious-metals Roth IRA guide offers background on the account type, but it cannot replace individualized tax advice. The structure works only when the investor can meet its rules and maintain records.
8. Beneficiary Designations and Wealth Transfer
A retirement portfolio can be diversified for more than the account owner's lifetime. Beneficiary designations, account types, and withdrawal planning may affect how heirs receive and eventually distribute retirement assets. The designation on an IRA generally deserves separate review because it may control the account transfer regardless of what an older will says.
Consider a household with $1 million in retirement savings, assigning $400,000 to a Roth Gold IRA and $600,000 to a Traditional IRA. The model separates assets by tax treatment and legacy objective, but it doesn't guarantee a better result. Heirs' tax brackets, distribution rules, state law, and the account owner's estate documents all matter.
Risk profile and trade-offs
A Roth account may be useful for legacy planning because qualified withdrawals can be tax-free, while Traditional IRA distributions generally create taxable income for heirs. A trust may be appropriate in some families, especially where the owner wants distribution conditions or coordinated management, but trusts require careful drafting and professional review.
The central risk is administrative. An outdated beneficiary form can produce an outcome that conflicts with the owner's current family circumstances.
Implementation steps
Review beneficiary forms after marriage, divorce, births, deaths, or major changes in heirs' financial circumstances. Coordinate the forms with a will and trust through an estate-planning attorney, and ask whether a trust satisfies current retirement-account requirements.
Explain the account location and basic distribution responsibilities to heirs. Beneficiaries should consult a tax professional before taking inherited IRA distributions, particularly when Traditional and Roth accounts are combined in the family plan.
8-Point Comparison: Precious Metals Diversification Strategies
| Strategy | Implementation complexity | Resource requirements | Expected outcomes | Ideal use cases | Key advantages |
|---|---|---|---|---|---|
| Asset Class Diversification: Precious Metals Within Retirement Accounts | Moderate, requires opening self-directed IRA and custodian setup | Custodian, secure storage, insurance, advisory input | Reduced portfolio correlation; inflation hedge; preserve purchasing power | Near-retirees/retirees seeking hedge within tax-advantaged account | Uncorrelated diversification; tax-deferred/tax-free growth access |
| Rollover Diversification: Converting 401(k)/Traditional IRA Into Precious Metals | Moderate–High, must follow IRS rollover procedures | Trustee-to-trustee transfers, paperwork, possible CPA/tax help | Consolidated accounts; reallocated asset mix without immediate tax if done correctly | Pre-retirees rolling over employer plans or consolidating IRAs | Avoids immediate taxation; simplifies holdings; enables deliberate allocation |
| Geographic & Geopolitical Diversification: Multiple Countries' IRA-Eligible Metals | Low–Moderate, select eligible foreign products and confirm purity | Access to international coins/bars, slightly higher premiums, custodian confirmation | Reduced single-country exposure; limited currency diversification benefit | Investors worried about geopolitical or country-specific currency risk | Spreads geopolitical/currency exposure across recognized mints/refiners |
| Precious Metals Mix Diversification: Gold, Silver, Platinum in One IRA | Moderate, manage different metals, purity rules, liquidity differences | Ability to buy multiple metal types, custodian storage, price monitoring | Spread metal-specific risk; varied volatility and industrial exposure | Investors seeking comprehensive precious-metals exposure within one IRA | Diversifies demand drivers (store-of-value vs industrial vs rarity) |
| Strategic Rebalancing & Dollar-Cost Averaging | Low, policy and cadence setup; discipline required | Regular contributions, custodial transaction support, record-keeping | Smoother entry prices; disciplined allocation maintenance over time | Long-term investors avoiding market-timing; retirees smoothing purchases | Reduces timing risk; enforces sell-high/buy-low discipline |
| Inflation-Hedging Diversification | Low, allocation decision and monitoring | Custodian, storage/insurance, periodic monitoring of inflation metrics | Potential preservation of purchasing power during inflationary periods | Retirees on fixed incomes or those fearing currency debasement | Historical inflation hedge; not dependent on issuer solvency; tax-advantaged compounding |
| Roth vs. Traditional IRA Diversification: Account-Structure Strategy | High, tax planning, possible conversions, coordination across accounts | Multiple IRA accounts, tax advisor/CPA, potential conversion tax payments | Optimized after-tax outcomes; differing RMD and withdrawal tax profiles | Investors managing lifetime tax efficiency and RMD exposure | Roth: tax-free withdrawals/no RMDs; Traditional: current-year tax deduction |
| Beneficiary Designations & Wealth Transfer Diversification | High, requires estate planning and coordination with tax law | Estate attorney, trusts (optional), coordinated beneficiary forms, tax planning | More efficient wealth transfer; potential tax savings for heirs (especially Roth) | Affluent retirees focused on legacy planning and intergenerational transfer | Avoids probate; Roth transfers can provide tax-free inheritance and continued growth |
Turning Diversification Examples Into a Written Retirement Plan
These diversification strategy examples are useful only when they become decisions with boundaries. A metals allocation without a target, review date, liquidity plan, and tax analysis can create the appearance of diversification while leaving the household exposed to one common risk. A U.S. brokerage-account study of more than 40,000 equity investment accounts examined during 1991–1996 found that many investors were materially under-diversified despite owning multiple securities. The NBER study reinforces the practical lesson: count holdings, but also measure portfolio weights, sector exposure, and correlations.
That diagnostic approach is especially important for precious metals. Physical bullion, metals exchange-traded funds, mining shares, and a metals IRA may look like separate holdings while remaining connected to the same broad theme. A household review should total every exposure before adding another account. The question isn't just how much gold sits inside an IRA. It's how much of the family's savings depends on metals prices, and what assets will fund withdrawals if metals decline.
The SEC's definition of diversification also supports a two-level review. The first level is the mix among categories such as stocks, bonds, cash equivalents, and potentially precious metals. The second is variety within each category. Several stock funds may still share the same economic exposure, just as several bullion products may respond to the same metals market.
A written plan can include:
- A target allocation: Record the intended range for stocks, bonds, cash, real estate, and precious metals.
- A risk purpose: State whether metals are intended to address inflation concerns, equity concentration, currency risk, or another defined exposure.
- A liquidity reserve: Identify which assets will fund near-term withdrawals without forcing a sale of volatile holdings.
- A review schedule: Use a calendar review or a predetermined drift threshold, then apply the same rule consistently.
- A cost record: Include setup, custody, storage, insurance, transaction, and potential tax costs.
- A transfer procedure: Confirm whether a trustee-to-trustee rollover is available before requesting retirement funds.
Rebalancing can restore the target through sales, purchases, or changes to ongoing contributions. The SEC identifies all three methods, which means a retiree doesn't always need to sell an appreciated holding immediately. Directing new money toward an underweighted category may be more practical, depending on income and account rules.
Investors should also test whether the proposed diversification survives different economic regimes. Recent institutional research warns that stock and bond correlations can become positive during inflationary or stagflationary periods, weakening a traditional hedge. MSCI's diversification research recommends considering asset class, country, industry, investment style, and risk model rather than assuming that familiar categories always offset one another.
Interest in precious metals also shouldn't be confused with proof that a large allocation is appropriate. An 2026 survey reported that 37% of advisors planned to increase precious-metals allocations and 54% planned to increase alternatives, while a separate investor survey found respondents held an average of 33.3% of savings and investments in precious metals and 47.4% planned to buy more bullion in 2026. Aberdeen Investments' analysis presents the relevant warning: growing enthusiasm can reflect concentration risk rather than sound diversification.
A broadly diversified portfolio analyzed by Morningstar returned 18.3%, compared with 13.3% for a standard 60/40 portfolio, and included 5% allocations each to commodities, gold, and REITs. Those figures are historical analysis, not a forecast or recommended allocation, but they illustrate why a diversified model may use several complementary exposures instead of concentrating heavily in one alternative asset. The investor's next step should be deliberate, not reactive.
Before moving retirement funds, select one or two strategies that fit the household's tax position, time horizon, liquidity needs, and risk tolerance. Write down the target allocation, the reason for each holding, the review schedule, and the conditions that would trigger a change. Confirm current IRS eligibility rules and all costs with a licensed financial advisor, CPA, or tax professional. This is not financial advice.
Gold IRA Association provides educational articles, rollover guides, fee explanations, and comparative information about precious-metals retirement accounts. As a practical next step, compare providers by custody arrangements, storage options, total costs, product eligibility, and reputation before committing retirement assets.
Gold IRA Association offers educational resources on Gold and Silver IRAs, rollover procedures, IRS-approved metals, fees, and provider comparisons. Readers can use its guides and reviews to prepare questions before choosing a custodian or moving retirement funds, then visit Gold IRA Association to continue the research.