

Most U.S. bank deposits are protected by FDIC insurance up to $250,000 per depositor, per insured bank, per ownership category. That protection is strong, but the answer to “is our money safe in the bank” depends on how the account is owned, whether the bank is FDIC-insured, and how much money sits above the applicable limit.
A person can hold several accounts at one bank and still have a large uninsured balance without realizing it. Deposit insurance also doesn't guarantee instant access during a bank disruption, protect investments from market losses, or preserve purchasing power when prices rise.
What Bank Deposit Insurance Actually Protects
The better question isn't just whether a bank is safe. It's whether a specific depositor's eligible deposits are fully covered if that bank fails.
For customers of an FDIC-insured bank, coverage is automatic. No separate policy must be purchased, and the protection generally applies dollar-for-dollar to principal plus accrued interest through the date of failure. Eligible products include checking accounts, savings accounts, certificates of deposit, and certain money-market deposit accounts. The FDIC's deposit insurance basics explains that the standard limit is $250,000 per depositor, per insured bank, per ownership category.
That last phrase matters most. The limit usually applies to the combined balance of accounts in the same legal ownership category, not to each account number. A checking account and savings account owned individually at one bank generally count together.
Three risks that deposit insurance doesn't erase
Credit risk is the possibility that the bank fails. FDIC insurance is designed to address eligible deposit losses within the coverage limit.
Liquidity and access risk are different. A bank can have valuable assets and still struggle to meet immediate withdrawals if those assets can't be converted to cash quickly without a major discount. Federal Reserve lending facilities can help eligible institutions meet short-term liquidity needs, but they don't turn every bank asset or depositor balance into a risk-free holding. The Federal Reserve's discount-window explanation describes those lending arrangements.
Inflation risk is separate again. A fully insured balance can lose purchasing power when prices rise. Deposit insurance protects against covered bank-failure losses, not every financial concern.
For readers considering retirement diversification, how a Gold IRA works provides background on a structure that holds approved physical metals through a custodian and depository rather than as a conventional bank deposit.
How FDIC Ownership Categories Determine Your Coverage Limit
Ownership categories are the practical math behind deposit insurance. Two accounts with different account numbers don't automatically receive two separate limits if the same person owns both in the same legal capacity.
| Ownership Category | Coverage Limit |
|---|---|
| Individual accounts | $250,000 per owner at one insured bank |
| Qualifying joint accounts | $250,000 per co-owner at one insured bank |
| Certain eligible retirement accounts | $250,000 per owner at one insured bank |
| Certain revocable-trust accounts | Up to $250,000 per owner per eligible beneficiary when requirements are met |
These limits and category rules are described by the FDIC deposit insurance calculator. The calculator should be treated as a verification tool, not as permission to assume that any account label creates additional coverage.
Why account numbers can mislead
Suppose one person has an individual checking account with $150,000 and an individual savings account with $140,000 at the same insured bank. The total individual ownership balance is $290,000, so the amount above the applicable individual limit isn't automatically insured.
Moving money from one individual account to another doesn't solve the issue. A second individual account remains in the same ownership category.
A qualifying joint account can be treated differently. Joint coverage may apply separately because the legal owners are different, but the account must meet the applicable requirements. Retirement accounts can also have their own category, while trust coverage depends on ownership and beneficiary details.
Practical rule: Several account numbers don't create several insurance limits. Legal ownership, bank charter, and beneficiary structure determine the calculation.
Deposits at separately chartered insured banks are insured separately. That can make spreading excess cash across institutions useful, but the bank must be a separate insured institution. A different branch or branded product isn't necessarily a different bank.
Real Bank Failures and What Happened to Depositors
Bank failures show why coverage limits matter more than reassuring account labels.
Between 2001 and 2020, 561 U.S. banks failed, involving approximately $721 billion in assets and $522 billion in deposits, according to the Congressional Research Service overview of deposit insurance. The figures don't mean that every depositor lost money. They show that failure remains possible even within an insured system.
Washington Mutual's 2008 failure was the largest U.S. bank failure in nominal terms, involving about $307 billion in assets and $188 billion in deposits. In that period, Congress temporarily increased the basic FDIC coverage limit from $100,000 to $250,000, and the higher limit later became permanent through the Dodd-Frank Act.
What 2023 made visible
The failures of Silicon Valley Bank and Signature Bank in 2023 involved roughly $319 billion in combined assets and $264 billion in combined deposits. Approximately 90% of the deposit base at those two banks was uninsured, which made the institutions especially exposed to withdrawals by customers holding large balances above the statutory limit.
At Silicon Valley Bank, approximately 94% of domestic deposits were uninsured. The uninsured balances fell sharply during the run, while fully insured retail deposits generally remained stable or increased. More than $40 billion was withdrawn in about eight hours during the Silicon Valley Bank episode. These figures are reported in the European Central Bank analysis of digital banking and deposit outflows.
Regulators protected all deposits in those particular failures under a systemic-risk exception. That action shouldn't be treated as a universal promise for uninsured funds.
If an acquiring bank assumes the deposits, insured customers generally retain access through the new institution. If no acquirer takes the deposits, the FDIC can pay the insured balance directly. Amounts above the limit become claims against the failed bank's receivership and may be recovered later, in whole or in part.
How to Audit Your Actual Deposit Exposure
A deposit audit turns an abstract insurance rule into a household balance sheet. The aim is to identify who owns each balance, where it sits, and how much falls within the applicable protection.
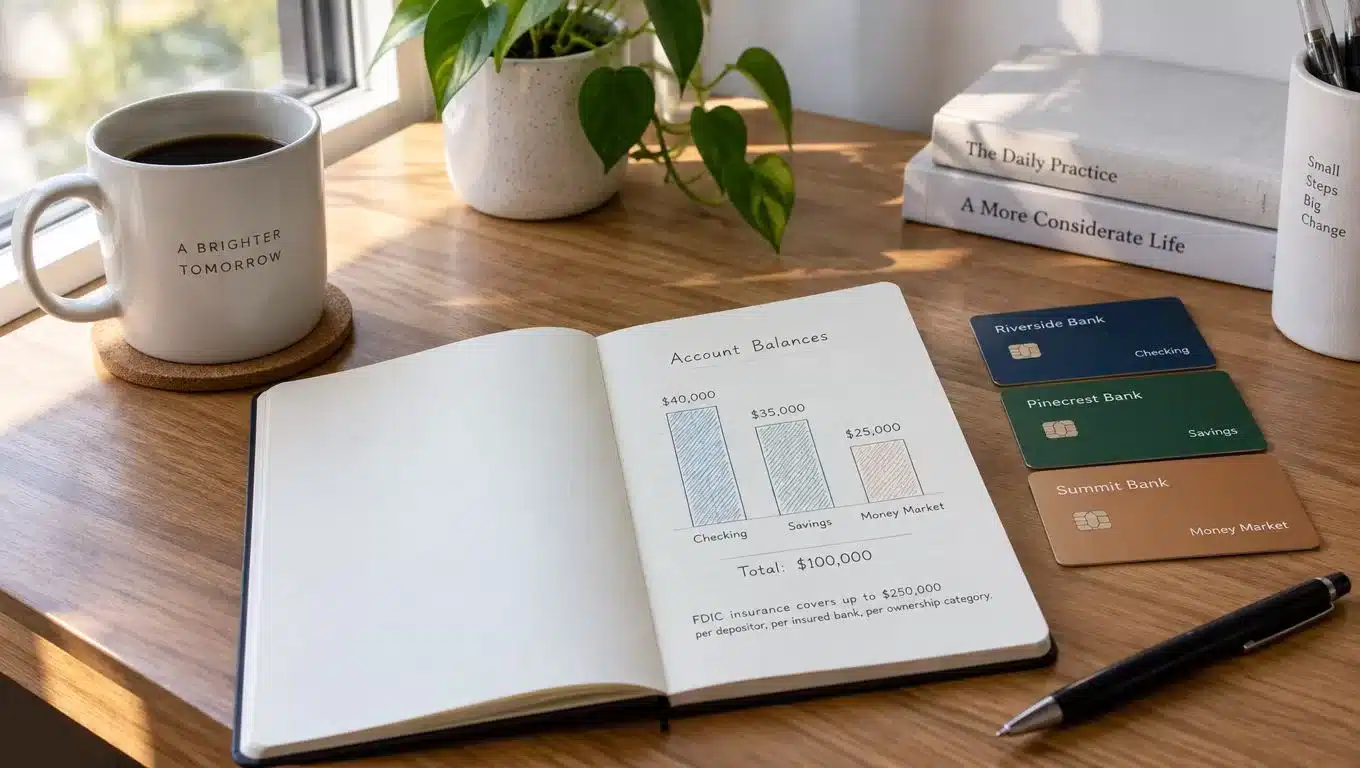
Create a simple list with these columns:
- Legal owner: Record whether the money belongs to one person, multiple people, a retirement account, or a trust.
- Institution: Identify the actual FDIC-insured bank and confirm whether another brand uses the same charter.
- Account type: Include checking, savings, certificates of deposit, and other deposit products.
- Balance and interest: Use the current balance and remember that accrued interest counts toward coverage.
- Beneficiaries: Note beneficiary designations and trust terms because they can affect category treatment.
Then combine accounts that share the same owner, bank, and ownership category. Don't count each account separately. Subtract the applicable insured limit from the combined amount only after the ownership classification has been checked.
A practical exposure example
A person with $180,000 in individual savings and $110,000 in individual certificates of deposit at the same bank has $290,000 in that ownership category. The first $250,000 falls within the standard limit, while the remaining $40,000 isn't automatically protected.
The depositor could discuss moving excess cash to a separately chartered insured bank, using a qualifying ownership structure where appropriate, or choosing another suitable holding. A deposit-placement service such as CDARS may help distribute deposits among participating institutions, but its terms, availability, and coverage structure must be verified before use.
Short-term Treasury securities are another possible cash-management option, though they aren't FDIC deposits and carry their own price and liquidity considerations. The important step is to compare the legal protection and access features rather than assume that every cash-like product works the same way.
Diversifying Beyond Traditional Bank Deposits for Retirement Savings
Bank deposits serve important purposes, especially for near-term spending and emergency reserves. Retirement savings, however, may need more than a single type of protection. A broader plan can separate payment liquidity, principal stability, inflation concerns, and long-term investment risk.
How common choices differ
Treasury securities are obligations of the U.S. government rather than bank deposits. They aren't covered by FDIC insurance, and their market value can change before maturity. They may still play a role in a cash or retirement allocation, depending on the investor's goals and time horizon.
Money-market funds are investment products, not money-market deposit accounts. They generally don't receive FDIC deposit insurance, and their value and access rules depend on the fund and account arrangement.
CDARS and similar deposit-placement arrangements can help a depositor access multiple bank relationships through one service. The depositor should confirm which banks hold the money, how coverage is allocated, and what happens if a participating institution fails.
Gold and silver IRAs address a different objective. A self-directed retirement account can hold eligible physical precious metals through a custodian and approved depository. Metals may provide portfolio diversification beyond bank deposits, but they can fluctuate in value, involve fees, and don't provide FDIC insurance or guaranteed returns. The Gold IRA Association guide to hedging against inflation discusses the role precious metals may play in a broader retirement strategy.
For readers reviewing account structures and retirement options, Duncan & Associates retirement account solutions offers another educational resource to consider alongside guidance from qualified professionals.
A retirement account may also involve tax rules, custodial arrangements, distribution requirements, and investment restrictions. Gold IRA Association is an information resource that explains Gold and Silver IRA structures, rollover procedures, eligible metals, fees, and provider comparisons. Its materials can help a reader prepare questions, but they don't replace individualized tax, legal, or investment advice.
The video below offers additional context for readers comparing retirement and savings choices.
Practical Steps to Keep Your Savings Secure
A sound plan doesn't require predicting the next bank failure. It requires knowing where the money is, what protection applies, and how the household would function if access were temporarily disrupted.
Use this checklist
- Confirm insurance status: Verify that each institution is an FDIC-insured bank. Don't rely only on a familiar brand name or the word “cash” in a product description.
- Group balances correctly: Combine individual accounts at the same bank before comparing the total with the applicable limit.
- Review ownership details: Check joint owners, retirement-account titles, trust documents, and beneficiary designations. A label alone doesn't guarantee separate coverage.
- Separate institutions when appropriate: Excess deposits may be spread across separately chartered insured banks after fees, access, and administrative complexity are considered.
- Protect payment access: Keep a practical backup for essential bills, such as another insured institution or another payment channel. Insurance doesn't guarantee that an app, card, or transfer rail will work without interruption.
- Match assets to purpose: Keep near-term spending money liquid, while evaluating longer-term retirement assets separately from the emergency reserve.
Digital banking can make withdrawals and transfers happen quickly during stress. That convenience also means a household shouldn't assume that a resolution will feel effortless. A second institution can provide operational resilience, even when the primary balance is insured.
The retirement planning checklist resource can help organize questions and documents before a conversation with a licensed financial advisor, CPA, or tax professional.
This is not financial advice. Consult a licensed financial advisor, CPA, or tax professional before making investment decisions.
Key Takeaways and Next Steps for Savers
The answer to “is our money safe in the bank” is conditional but reassuring for properly covered deposits. FDIC insurance has protected eligible depositors up to their insured limits since federal deposit insurance began in 1934. The original limit was $2,500, it increased to $5,000 in 1934, and the standard limit is now $250,000 per depositor, per insured bank, per ownership category, as documented in the FDIC history of deposit insurance.
The practical concern is hidden concentration. Several accounts at one bank may be combined, while money above the applicable limit can face delay, loss, or dependence on extraordinary government action. Deposit insurance also doesn't protect stocks, bonds, mutual funds, cryptocurrency, purchasing power, or every product marketed through a bank.
A careful saver can take three actions:
- Map each balance by legal owner, bank charter, account type, and beneficiary structure.
- Confirm the amount that falls within the applicable FDIC category limit.
- Decide whether excess cash should remain in deposits, move across separately insured institutions, use another cash-management structure, or support a diversified retirement allocation.
This is not financial advice. Consult a licensed financial advisor, CPA, or tax professional before making investment decisions.
Gold IRA Association offers educational guides on Gold and Silver IRAs, rollovers, eligible metals, custodians, storage, fees, and provider comparisons. Visit Gold IRA Association to review diversification resources and request information before discussing whether precious metals fit a broader retirement plan.